If you own — or are about to buy — an apartment in Vietnam and plan to rent it out, the rent you collect is taxable here, even though you live abroad and the money may never touch a Vietnamese bank account you control day to day.
The good news is that the regime for individual landlords is simple and the rates are low; the catch is that the rules are changing in 2026, the thresholds moved, and you have to register and declare correctly to keep your money flowing out of the country.
The two taxes on individual rental income: VAT + PIT
When a private individual (Vietnamese or foreign) leases out residential property, Vietnam does not tax the profit. It applies two flat, presumptive taxes to the gross rent:
Value-added tax (VAT)- Personal income tax (PIT) at 5%.
That is a combined headline rate of roughly 10% of gross rent. There is no deduction for expenses, management fees, mortgage interest, repairs, furniture, or depreciation — the rate is applied to the rent itself, which is what makes the individual regime so administratively light.
This presumptive 5% + 5% treatment is specific to property leasing (along with a few other service categories); it is not the progressive PIT scale that applies to salaries.
For most foreign owners of one or two apartments, this is the regime you will be in. If you want the operational side of being a landlord — leases, furnishing, finding tenants, handling deposits — see our companion guide on renting out your apartment in Vietnam.
The 2026 thresholds: when rent becomes taxable
| Period | What it means | |
|---|---|---|
| Up to 31 Dec 2025 | VND 100 million | |
| From 1 Jan 2026 | VND 200 million | Threshold doubled under the new framework |
| From 1 Jul 2026 | VND 500 million | Amended PIT Law lifts it to ~US$19,000/year |
In practice this is a generous lift. From the second half of 2026, a foreign owner whose apartment earns under roughly VND 500 million a year (about
A few honest caveats. Public sources are not fully consistent on the timeline — some describe a single jump straight to VND 500 million in 2026, others (and the legislative record) describe the VND 200 million intermediate step from 1 January with the VND 500 million figure tied to the amended PIT Law from 1 July 2026.
Detailed implementing circulars were still being issued at the time of writing, and exact figures and effective dates can shift.
Treat the numbers above as indicative and confirm the live threshold before you rely on it.
How the tax is calculated (with a worked example)
PIT on the portion of rent above the threshold is straightforward:
PIT payable = (Annual gross rent − threshold) × 5%
The treatment of VAT is the point where public commentary diverges, and you should be aware of it. Some older guidance applied VAT to the entire gross rent once the threshold was crossed, while the most concrete 2026 worked examples in the Vietnamese press apply both the 5% PIT and the 5% VAT only to the amount above the threshold.
Worked example — a foreign owner of a Ho Chi Minh City apartment renting for VND 50 million/month = VND 600 million/year
| Item | Calculation | Amount (VND) |
|---|---|---|
| Annual gross rent | 50m × 12 | 600,000,000 |
| — | 500,000,000 | |
| Taxable base (excess) | 600m − 500m | 100,000,000 |
| VAT | 100m × 5% | 5,000,000 |
| PIT | 100m × 5% | 5,000,000 |
| Total annual tax | 100m × 10% | 10,000,000 |
| Effective rate on total rent | 10m / 600m | ~1.7% |
So a landlord earning VND 600 million a year pays around VND 10 million — roughly 1.7% of total rent, because only the slice above the threshold is taxed.
If the same apartment earned exactly VND 500 million or less, the tax would be zero. This is why rental tax rarely changes the underlying investment maths; for how the gross yield itself stacks up, see rental yield in Ho Chi Minh City.
The business-license fee is gone from 2026
There is a second piece of good news. Historically, individuals running a leasing “business” could be liable for an annual business-license fee (lệ phí môn bài) on top of VAT and PIT.
Under Resolution No. 198/2025/QH15, this license fee is abolished from 1 January 2026 for household and individual businesses — including those leasing property.
For a foreign landlord that removes a small annual charge and one more filing obligation. Combined with the higher thresholds, the direction of travel in 2026 is clearly toward less
Getting a tax code and registering
You cannot pay rental tax — or, in practice, remit the rent abroad — without a Vietnamese tax code. A foreign individual earning rental income must register at the district tax office where the property is located. Key points:
- The rental tax code is separate from any tax code tied to employment income in Vietnam.
- You can register in person, or through an authorized representative using a notarized power of attorney (POA) — this is the normal route for owners who live abroad.
- Banks generally require proof of tax payment before they will process an overseas transfer of rental income, so registration is not optional if you ever want the money out of Vietnam.
The mechanics of getting documents notarized and legalized from overseas, and running the property remotely, are covered in our guide on managing your Vietnam property from abroad.
Who declares and when
You have two realistic models as a foreign owner:
- Declare yourself. You (or your POA holder) register the rental, file the declaration, and pay the tax directly to the tax authority.
- Have your management company or a tax agent do it.
Under a notarized POA, a property-management company, the agent collecting your rent, or a licensed tax-service firm can handle registration, periodic declarations, and payment on your behalf. Organizations can also declare on behalf of multiple individual landlords on a consolidated form.
Filing frequency depends on how the lease pays. Declarations are commonly made per payment under the lease, or on a
Whichever model you choose, the legal responsibility for a correct declaration stays with you as the owner — so pick a reputable agent and keep copies of every filing and receipt. A POA delegates the work, not the liability.
How it differs if a company holds the property
Some investors hold Vietnamese real estate through a company rather than in their personal name. The tax picture changes completely:
| Feature | Individual landlord | |
|---|---|---|
| Income tax | 5% PIT on gross rent above threshold | ~20% corporate income tax on net profit |
| VAT | 5% (presumptive, on leasing) | Standard-rate VAT (commonly 10%) on lease invoices |
| Yes (VND 200m → 500m in 2026) | No threshold — corporate rules from the first dong | |
| Expense deductions | None — flat on gross rent | Yes — deduct costs, depreciation, interest (net basis) |
| Compliance burden | Light (register + periodic filing) | |
| Business-license fee | Abolished from 2026 | Standard corporate fees apply |
For the typical foreign buyer of a single apartment, the individual regime is simpler and usually cheaper at small scale: a flat ~10% on the excess over a high threshold, no accounts to audit.
The company route can deduct real costs and can suit a larger portfolio, commercial leasing, or an investor already operating a Vietnamese entity — but it brings corporate income tax (around 20%), full accounting and audit obligations, and standard-rate VAT.
Which structure is right is a decision for a Vietnamese lawyer and tax adviser before you buy — not something to retrofit later.
The home-country angle: worldwide income and tax treaties
This is where
- a foreign tax credit
for the Vietnamese VAT/ - an exemption of the foreign-sourced rent, depending on the specific treaty and your residence rules.
Two practical points. First, treaty relief generally covers income tax, and is limited to tax actually paid in Vietnam — which is another reason to keep clean records and receipts.
Do not assume your Vietnamese tax is the end of it — confirm the reporting and credit position with a tax adviser in your country of residence.
How rental tax fits the total cost of ownership
Key takeaways
- Individual foreign landlords pay 5% VAT + 5% PIT (~10% combined) on rent above an annual threshold — no expense deductions.
The VND 500 million per year in 2026 (amended PIT Law; via a VND 200 million intermediate step from 1 January); figures are indicative while circulars are finalised.tax-free threshold rose in steps to- The business-license fee is abolished from 2026 (Resolution 198/2025/QH15).
- You need a Vietnamese tax code; a management company or tax agent can declare and pay under a notarized POA, but the liability stays with you.
- A
company-held - Your home country likely taxes the income too; DTAs and foreign tax credits prevent double taxation, but the mechanics vary by country.
Before acting, consult a licensed Vietnamese lawyer and tax adviser, and a tax adviser in your country of residence.
Thinking about buying a Vietnamese apartment to rent out, and want the tax and yield numbers run on a specific unit? Message Happy Land on Zalo or WhatsApp — we sell at the developer’s price with live inventory and can walk you through the post-purchase rental and tax picture before you commit. Browse our project listings to start.
Frequently asked questions
How much tax does a foreigner pay on rental income in Vietnam?
Do I need a Vietnamese tax code to rent out my apartment?
Yes. A foreign individual earning rental income in Vietnam must register for a personal tax code at the district tax office where the property is located before declaring and paying tax. You can register in person, or appoint a representative — often your property-management company or a tax agent — using a notarized power of attorney. The rental tax code is separate from any tax code tied to employment income. Banks typically ask for proof that tax has been paid before they will let you remit rental income abroad, so staying registered and current matters for getting your money out.
Can my property manager declare and pay the rental tax for me?
Yes. Many overseas owners give their management company or a licensed tax agent a notarized power of attorney to handle tax registration, periodic declarations, and payment on their behalf. The legal liability for correct declaration still rests with you as the owner, so use a reputable agent and keep copies of every filing and payment receipt. Filing is generally done per lease payment, or twice a year / annually depending on how the lease is structured, with common deadlines around 31 January and 31 July.
Is rental income from Vietnam taxable in my home country too?
Is it better to hold a Vietnamese rental property through a company?
For most individual foreign buyers of a single apartment, no. A Vietnamese company holding property is taxed under the corporate regime — roughly 20% corporate income tax on net profit plus standard-rate VAT on leasing — and carries accounting, audit, and compliance costs that rarely make sense for one unit. The individual landlord regime (flat ~10% on gross rent above the threshold, with the business-license fee abolished from 2026) is simpler and usually cheaper at small scale. Company structures can suit larger portfolios or commercial leasing, but that is a decision for a Vietnamese lawyer and tax adviser, not a default.
Projects for sale now
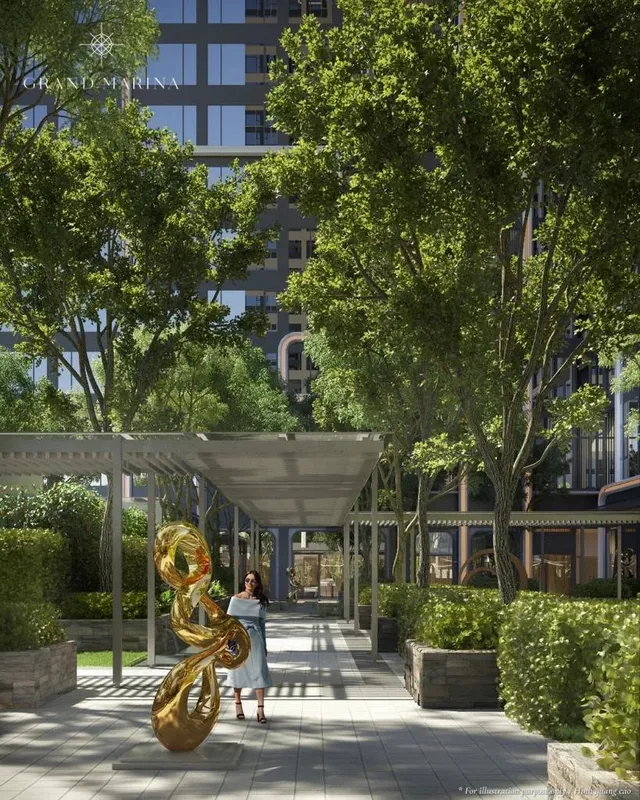
Selling now Foreign quota
Masterise Homes · Branded Residences
Grand Marina Saigon
District 1, Ho Chi Minh City
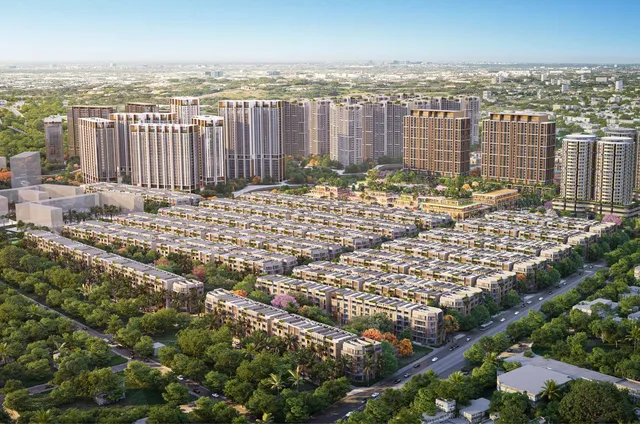
Selling now Foreign quota
Masterise Homes · Luxury apartment & integrated township
The Global City
Binh Trung Ward (former An Phu Ward, Thu Duc City), Ho Chi Minh City
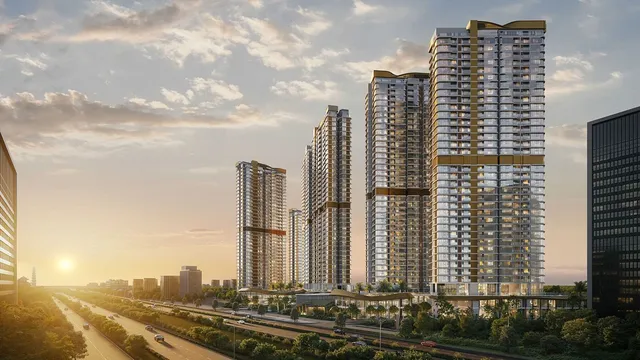
Selling now Eligibility: ask
Gamuda Land · Luxury apartment
Eaton Park
An Phu, Thu Duc City, HCMC