Over the past couple of years, foreign owners of Vietnamese property have read alarming headlines: “20% tax on property gains,” “hold it less than two years and pay 10%.”
Many concluded that from 2026 selling would cost them a fifth of their profit, or that quick sales would be punished by a holding-period tax.
The 2026 reality is different. This guide separates what was proposed from what is actually in force, so foreign sellers can plan around the real rule rather than the scary headline — and keep the right records in case the rules change later.
What you read in the news: two options that were proposed
While redrafting the Personal Income Tax law, Vietnam’s Ministry of Finance floated tougher ways to tax property transfers, aimed at curbing speculation and “flipping.” Two ideas drew the most attention.
Option 2 — a holding-period schedule. The idea was that the shorter you held, the higher the rate, to discourage rapid buying and selling.
This was floated mainly as a fallback for when the purchase price cannot be determined (so a gain cannot be computed), with the tax applied to the sale price at rates such as:
| Holding period | Rate discussed |
|---|---|
| Under 2 years | 10% |
| 2 to under 5 years | 6% |
| 5 to under 10 years | 4% |
| 10 years or more, or from inheritance | 2% |
These two proposals are the source of the “flip tax” and “20%” headlines. The crucial point: they were proposals in a draft, not rules that took effect.
Why the tougher options were dropped
Both ideas ran into the same wall: practical complexity, especially determining the real purchase price and having the data to do it.
To tax 20% of the gain, the authority must know your true purchase price and allowable costs — sometimes from years ago, across several resales, with incomplete paperwork.
In a market where the price written on a notarized contract has not always matched the real transaction price, reconstructing a fair “gain” is difficult and invites disputes.
The holding-period option hit the same data problem. Because of these concerns, the profit and holding-period methods were dropped from the draft, and the drafters kept the simpler, more transparent method: 2% on the transfer price.
So how is it taxed now? Still 2% on the sale price
Here is the practical answer for most sellers in 2026: a resident individual’s personal income tax on a property transfer remains 2% of the transfer price, per transaction, unchanged in substance from the long-standing rule. The formula is simply:
PIT = transfer price × 2%
Two things follow. First, it is charged on the sale price, not the gain, and does not vary with how long you held the property — six months or ten years, the current 2%-on-price is the same.
Second, because it is on gross price,
For the full set of exit costs and the repatriation side, see selling property in Vietnam & foreigner taxes and repatriating funds from a sale
Note that exemptions exist — for example a sole home held at least 183 days, and certain family gifts or inheritance — so check whether any apply before assuming the 2% is due.
Could a profit-based or holding-period tax come back?
Dropped does not mean gone forever. The government has signalled that taxing property transfers on the gain could be studied again in the future, once the land database is fully digitized and linked to the VNeID electronic-ID system.
In other words, this is an open direction, not a closed door. A sensible foreign investor does not ignore it, even though it does not apply today.
What it means for foreign sellers and investors
A few practical takeaways:
- Plan around the rule that is in force. If you are selling in 2026, compute your costs on the 2%-of-price basis, not the headline 10% or 20%.
Keep records as if a Preserve your documented purchase price, improvement and transaction costs, and the inbound banking trailgain-based tax will return.from when you bought. If a repatriating your proceeds regardless.profit-based tax ever applies, this evidence lets you prove costs and reduce the taxable gain — and it is essential forMind the cross-border angle.A future Vietnamese capital-gains tax in your home countrygain-based tax could interact withand any double-tax treaty. Confirm both sides with across-border adviser before selling.- Holding period still matters — for market reasons, not tax. Short flips carry high transaction-cost and timing risk; the case for a longer hold rests on the market and net yield, not on today’s tax. For that bigger picture see is Vietnam real estate a good investment in 2026 and property capital appreciation.
Conclusion
The “20% flip tax” and “holding-period tax” headlines reflect options that were considered, not rules that took effect.
As a primary-market distributor in Ho Chi Minh City, Happy Land can help you understand the exit costs on a specific unit and structure a purchase with clean records from day one. Browse current projects or contact our team on Zalo or WhatsApp.
Frequently asked questions
Will Vietnam tax my property gains at 20%?
Is there a holding-period tax that hits quick flips harder?
It was proposed, then dropped. The floated schedule taxed the sale price at rates that fell with how long you held — commonly cited as 10% under 2 years, 6% for 2 to under 5 years, 4% for 5 to under 10 years, and 2% for 10 years or more or from inheritance — mainly as a fallback for when the purchase price cannot be determined. It is not in force. Currently the tax is a flat 2% on the transfer price regardless of how long you held the property.
Why were the profit and holding-period options dropped?
The 2% is on the sale price, not profit — so I pay even if I sell at a loss?
As a foreign seller, what should I do now?
Projects for sale now
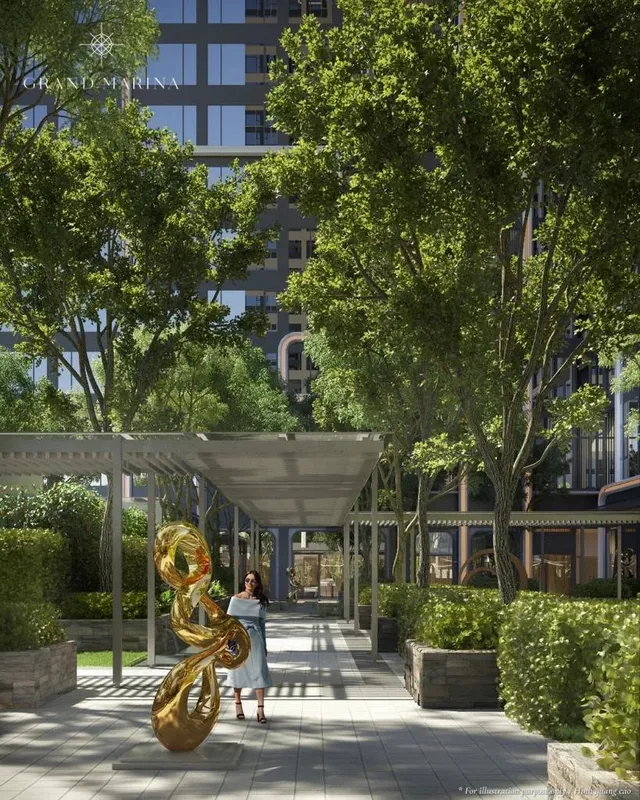
Selling now Foreign quota
Masterise Homes · Branded Residences
Grand Marina Saigon
District 1, Ho Chi Minh City
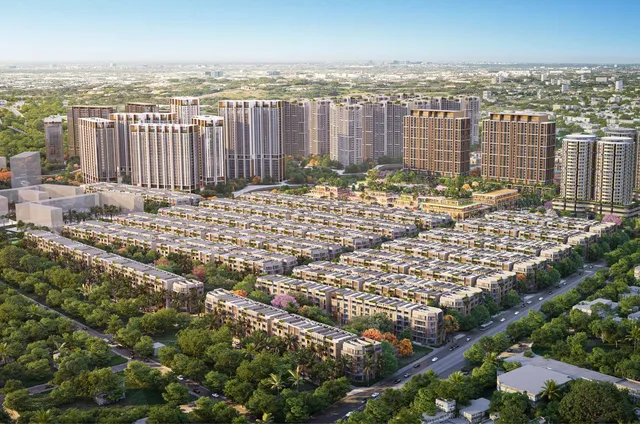
Selling now Foreign quota
Masterise Homes · Luxury apartment & integrated township
The Global City
Binh Trung Ward (former An Phu Ward, Thu Duc City), Ho Chi Minh City
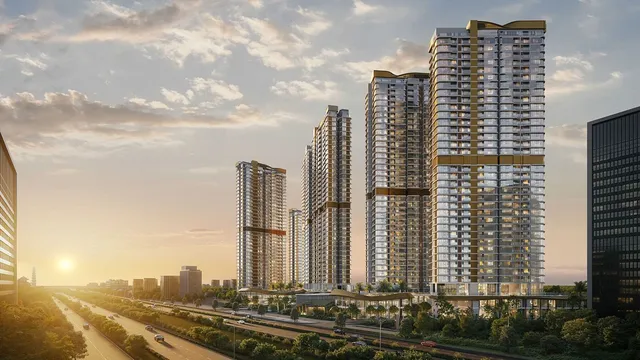
Selling now Eligibility: ask
Gamuda Land · Luxury apartment
Eaton Park
An Phu, Thu Duc City, HCMC